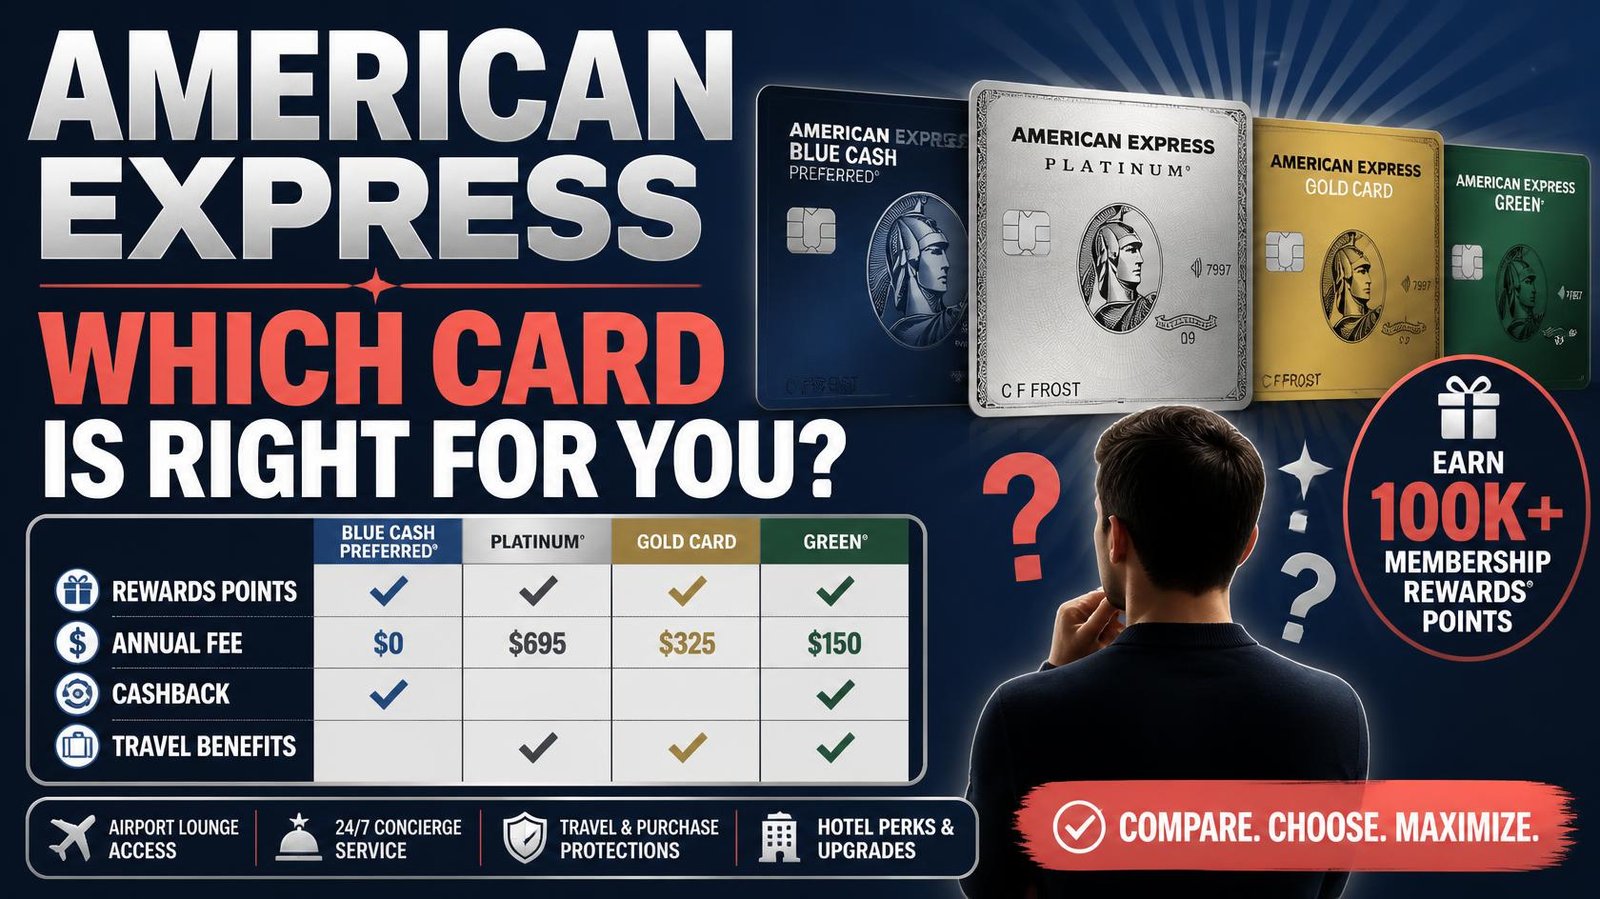
Choosing a credit card can feel simple until you start comparing rewards, annual fees, welcome offers, travel benefits, cash back, and interest rates.
American Express offers several types of credit cards designed around different spending patterns. Some focus on everyday cash back, while others are built around Membership Rewards points, travel benefits, dining, or premium perks.
The important question is not simply “What is the best American Express credit card?”
A better question is:
Which American Express card fits the way you actually spend and manage money?
American Express currently groups its U.S. consumer cards into categories that include cash back, Membership Rewards points, travel, airline, hotel, dining, and other features. The exact cards, fees, rewards and introductory offers can change, so applicants should always review the current terms before applying.
This guide explains the major American Express credit card options, how their reward systems work, what fees to consider, and how to narrow down your choices without choosing a card simply because it has a large welcome offer.
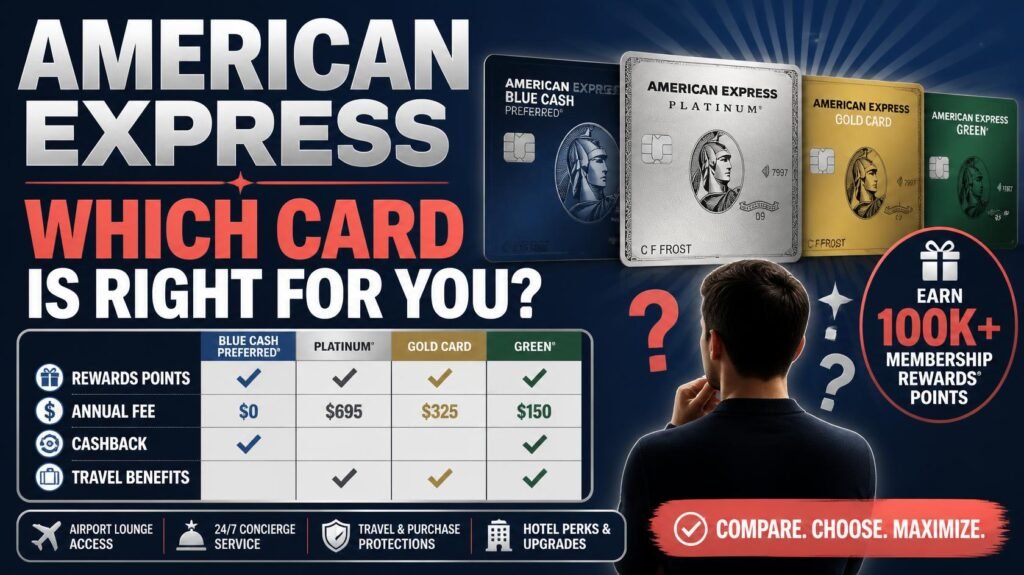
American Express Credit Cards at a Glance
American Express cards generally fall into a few major groups:
| Card Type | Main Focus | May Suit |
| Cash Back Cards | Cash back on everyday purchases | Everyday shoppers |
| Membership Rewards Cards | Flexible points | People who want points |
| Travel Cards | Travel rewards and benefits | Frequent travelers |
| Premium Travel Cards | Travel perks and credits | Frequent travelers who can use the benefits |
| Airline Cards | Airline-specific rewards | Frequent flyers with a preferred airline |
| Hotel Cards | Hotel rewards and benefits | Regular hotel guests |
| No Annual Fee Cards | Simple rewards without an annual fee | Cost-conscious users |
American Express itself describes its U.S. cards as having different reward structures and benefits rather than being simple “levels” of the same card. The right option depends heavily on spending habits and lifestyle.
What Makes American Express Credit Cards Different?
One of the biggest differences among Amex cards is the way rewards work.
Some American Express cards earn Reward Dollars, which function as cash back and can generally be redeemed as statement credits. Other cards earn Membership Rewards points, which can offer different redemption options depending on the card and program terms.
This distinction matters because two cards can both reward spending while giving you very different types of rewards.
For example:
- A cash back card may be easier to understand.
- A Membership Rewards card may offer more flexibility for someone interested in travel.
- A premium card may offer valuable benefits but charge a higher annual fee.
- A no-annual-fee card may be more appropriate for someone who wants a simpler long-term setup.
The best choice depends on what you will actually use.
American Express Cash Back Credit Cards
If you prefer straightforward rewards instead of managing points, American Express offers cash back options.
Two major examples are the Blue Cash Everyday® Card and Blue Cash Preferred® Card.
Blue Cash Everyday® Card
The Blue Cash Everyday Card is designed around everyday spending and has no annual fee.
American Express currently lists 3% cash back on eligible U.S. supermarket purchases, U.S. online retail purchases, and U.S. gas station purchases, subject to annual spending limits and other terms. Purchases outside those bonus categories generally earn 1% cash back.
This type of structure may appeal to someone who wants:
- No annual fee
- Cash back instead of points
- Rewards on groceries
- Rewards on eligible online shopping
- Rewards on eligible gas purchases
- A relatively simple rewards system
The important detail is that the higher reward rates have spending caps and category definitions. For example, not every store that sells groceries necessarily qualifies as a U.S. supermarket under the card’s terms.
Who should consider Blue Cash Everyday?
It can make sense for someone who wants a no annual fee American Express credit card and regularly spends in its eligible everyday categories.
It may be particularly interesting for someone who does not want to calculate whether a premium card’s annual benefits justify its cost.
Blue Cash Preferred® Card
The Blue Cash Preferred Card is another cash back option, but it has a different reward structure and an annual fee after its introductory first-year period under the current terms.
American Express currently lists 6% cash back at U.S. supermarkets on eligible purchases up to the applicable annual limit, 6% on select U.S. streaming subscriptions, and 3% on transit and eligible U.S. gas station purchases. Other eligible purchases generally earn 1%.
That makes the card particularly relevant to households with substantial spending in categories that receive higher rewards.
But there is an important calculation to make.
If a card charges an annual fee, the additional rewards you earn need to provide enough value to justify that fee.
Blue Cash Everyday vs. Blue Cash Preferred
| Feature | Blue Cash Everyday | Blue Cash Preferred |
| Annual fee | $0 under current terms | $0 introductory fee, then annual fee under current terms |
| Supermarket rewards | 3% on eligible U.S. supermarket purchases up to applicable limit | 6% on eligible U.S. supermarket purchases up to applicable limit |
| Online retail | 3% on eligible U.S. online retail purchases up to applicable limit | Not the same primary bonus category |
| Streaming | Different benefits | 6% on select U.S. streaming |
| Gas | 3% on eligible U.S. gas purchases up to applicable limit | 3% on eligible U.S. gas purchases |
| Transit | Not the primary bonus category | 3% on eligible transit |
| Best suited to | Simple everyday cash back | Higher spending in bonus categories |
Current terms and benefits should be checked before applying because American Express can change offers and card terms.
American Express Membership Rewards Credit Cards
If you are more interested in points than straightforward cash back, American Express has cards that participate in the Membership Rewards® program.
Membership Rewards points can be used through different redemption options depending on the card and applicable program rules.
American Express states that eligible Membership Rewards points generally do not expire as long as the Card Member maintains at least one active enrolled card, subject to the program terms.
This type of rewards system can be useful for people who want flexibility rather than simply receiving cash back.
Potential uses can include:
- Travel-related redemptions
- Flights
- Hotels
- Gift cards
- Other available redemption options
- Transfers to participating loyalty programs where permitted
The value of points can vary depending on how they are redeemed, so you should not automatically assume that one point has a fixed cash value.
American Express Gold Card
The American Express® Gold Card is designed around rewards and benefits associated with categories such as dining and travel.
American Express currently lists a $325 annual fee for the U.S. Gold Card and describes benefits connected with eligible dining and travel purchases.
A card with an annual fee should be evaluated differently from a no-annual-fee card.
Instead of asking:
“Does this card have good rewards?”
ask:
“Will I actually use enough of its benefits to make the annual fee worthwhile?”
For someone who regularly spends in eligible dining and other bonus categories, the answer could be different from someone who rarely uses those categories.
American Express Platinum Card
The The Platinum Card® from American Express is positioned toward premium travel and benefits.
The current U.S. American Express listing highlights benefits such as Membership Rewards points on eligible prepaid hotels and flights booked through American Express Travel and access to the American Express Global Lounge Collection.
This is the type of card where the annual fee is only one part of the equation.
A potential cardholder should look at:
- Airport lounge access
- Travel credits
- Hotel-related benefits
- Airline-related benefits
- Rewards earning
- Purchase protections
- Statement credits
- Annual fee
- Whether the benefits are actually usable
A long list of benefits does not automatically mean the card will provide value for every person.
American Express Travel Credit Cards
Travel-focused American Express cards can be useful for people who regularly book flights, hotels, or other eligible travel.
Depending on the specific card, benefits can include:
- Travel rewards
- Membership Rewards points
- Airline-related benefits
- Hotel-related benefits
- Airport lounge access
- Travel statement credits
- Travel protections
American Express currently lists travel, airline, hotel and lounge-access categories when browsing its U.S. credit card lineup.
Before choosing a travel credit card, look beyond the headline reward rate.
Consider how frequently you travel and whether the specific benefits match the way you travel.
For example, a benefit that requires booking through a particular platform may have less practical value if you normally book directly with airlines or hotels.
American Express Airline Credit Cards
American Express also offers co-branded airline cards, including cards connected with Delta SkyMiles.
These cards can be relevant to travelers who frequently use the associated airline and can benefit from airline-specific rewards or perks.
An airline credit card is most useful when its benefits match your normal travel behavior.
Before applying, check:
- Airline rewards structure
- Annual fee
- Free checked-bag benefits, if applicable
- Boarding or travel benefits
- Spending requirements
- Redemption rules
- Airline restrictions
- Current welcome offer
Do not choose an airline card simply because the introductory bonus looks large.
American Express Hotel Credit Cards
American Express also offers hotel-related cards, including cards associated with Hilton Honors and Marriott Bonvoy.
These can make sense for travelers who regularly stay with the associated hotel brands.
A hotel card should be evaluated according to the benefits you can realistically use, such as:
- Hotel rewards
- Elite-related benefits
- Free-night opportunities where applicable
- Hotel credits
- Annual fees
- Spending rewards
- Redemption flexibility
The actual terms vary by card, so check the current card agreement and benefit terms before applying.
How to Choose the Right American Express Credit Card
There is no single American Express card that is automatically right for everyone.
Instead, use a simple five-step process.
1. Identify Your Main Spending Categories
Look at your actual spending.
Do you spend more on:
- Groceries?
- Online shopping?
- Gas?
- Dining?
- Streaming?
- Travel?
- Hotels?
- Airline tickets?
- Transit?
Your spending pattern can reveal which rewards structure is most relevant.
American Express itself recommends comparing cards according to lifestyle and spending preferences rather than choosing solely based on the card’s headline benefits.
2. Decide Between Cash Back and Points
This is one of the biggest decisions.
Choose cash back if:
You want:
- Simple rewards
- Easy-to-understand earnings
- Statement credits
- Less rewards management
Consider points if:
You want:
- Travel-related redemption possibilities
- More flexible rewards options
- Membership Rewards
- Potential transfer opportunities where available
Neither approach is automatically better. The useful option is the one you will actually use.
3. Calculate the Annual Fee
An annual fee should never be ignored.
Suppose a card costs $95 per year.
If the additional rewards and benefits you realistically use are worth less than $95, paying the fee may not make financial sense.
If your spending generates significantly more value than the fee, the calculation changes.
A simple formula is:
Net Card Value = Rewards + Benefits You Actually Use − Annual Fee
This is not an official American Express formula. It is simply a practical way to compare cards.
4. Look at the APR
Rewards are only one side of a credit card.
The other side is the cost of borrowing.
The APR, or annual percentage rate, represents the cost of credit and is an important number to compare between cards. Credit card APRs can vary according to the card and other factors.
If you normally pay your statement balance in full, the purchase APR may be less important to your everyday rewards calculation than it would be for someone who regularly carries a balance.
Still, you should always understand the APR and other applicable charges before applying.
5. Check the Current Welcome Offer Carefully
American Express frequently provides welcome offers for eligible new Card Members.
But offers can vary by applicant, card, and time.
American Express’s current card listings explicitly state that welcome offers can vary and that an applicant may not be eligible for a particular offer.
Before applying, check:
- Required spending amount
- Time period
- Bonus amount
- Eligibility restrictions
- Annual fee
- Other applicable terms
A welcome bonus should be treated as an extra benefit—not a reason to spend money you would not otherwise spend.
American Express Credit Card Fees You Should Understand
The annual fee is only one possible cost.
Depending on the card and transaction, you may encounter:
- Annual fees
- Purchase APR
- Balance transfer fees
- Cash advance fees
- Late payment fees
- Foreign transaction fees
- Other account-related charges
The CFPB recommends looking beyond APR and considering the fees associated with holding and using a credit card.
Always read the current Rates and Fees and cardmember agreement before submitting an application.
What About the American Express Credit Card APR?
Credit card APR matters most when you carry a balance.
Many credit card issuers calculate interest daily based on the account’s balance or average daily balance, depending on the card’s terms. If a card provides a grace period for purchases, paying the balance in full by the due date can generally help you avoid interest on those purchases.
This is why a rewards card should not be viewed as “free money.”
For example, earning rewards on a purchase does not necessarily make sense if you pay substantial interest because you carry the balance.
Should You Pay Only the Minimum?
The minimum payment is the smallest amount required by the statement’s due date.
But paying only the minimum can extend repayment for a long time and increase the total interest you pay. The CFPB notes that paying more than the minimum can reduce interest costs and help pay down the balance faster.
For someone who wants to maximize credit card rewards responsibly, paying the statement balance in full when possible is an important part of the strategy.
Do American Express Credit Cards Help Build Credit?
A credit card can become part of your credit history, but simply having an Amex card does not automatically improve your credit score.
Credit outcomes depend on factors such as payment history, balances, credit utilization and other information contained in your credit reports.
The most important habit is making required payments on time.
Missing payments can have financial and credit consequences, while responsible account management can support a healthy credit profile over time.
American Express Credit Cards for Beginners
Someone new to credit may naturally search for the best American Express credit card for beginners.
Instead of focusing on a single card, beginners should consider a few questions:
Do you want an annual fee?
If not, look at no-annual-fee options.
Do you prefer cash back?
A cash back card may be easier to understand.
Do you want travel rewards?
A Membership Rewards or travel-oriented card may be more relevant.
Can you comfortably meet a welcome-offer spending requirement?
If not, do not increase spending simply to earn a bonus.
Can you pay the balance on time?
This should come before rewards.
For a beginner, a simple card that fits existing spending can often be easier to manage than a complicated premium rewards setup.
American Express Credit Cards: Pros and Cons
Potential Advantages
Multiple reward structures:
American Express offers cash back, Membership Rewards points, travel, airline and hotel-related cards.
Strong category rewards:
Some cards provide enhanced rewards for specific spending categories.
Travel benefits:
Selected Amex cards offer travel-related perks and benefits.
Amex Offers:
Eligible Card Members can add certain merchant offers to their cards and receive statement credits or other rewards when qualifying purchases meet the offer terms.
Digital account management:
The American Express app provides tools for monitoring account activity, payments and eligible offers.
Potential Drawbacks
Some cards have annual fees:
Premium rewards and travel cards can carry substantial annual fees.
Rewards can be complicated:
Different cards have different categories, spending limits and redemption rules.
Benefits require attention:
Some statement credits or offers may require enrollment or specific purchase conditions.
Interest can outweigh rewards:
Carrying a balance can make the cost of borrowing much greater than the rewards earned.
Offers can change:
Welcome bonuses, fees and benefits are not permanent.
American Express Credit Card Comparison: What Should You Look At?
When comparing Amex cards, create a simple checklist:
| Factor | Question to Ask |
| Annual fee | How much will I pay every year? |
| Rewards | What purchases earn the most? |
| Spending caps | Are bonus rewards limited? |
| Redemption | How can I use the rewards? |
| APR | What happens if I carry a balance? |
| Welcome offer | Can I meet the requirement naturally? |
| Travel benefits | Will I actually use them? |
| Credits | Do I normally make qualifying purchases? |
| Fees | Are there other transaction charges? |
| Long-term value | Would I keep the card after the first year? |
This approach helps prevent a common mistake: choosing a card because its advertisement looks impressive without checking whether the benefits match your real spending.
A Simple Example
Imagine two people.
Person A spends heavily on groceries, gas and online shopping but rarely travels.
A cash back American Express card may fit this spending pattern better because the rewards are connected to everyday purchases.
Person B travels regularly and wants travel-related benefits and Membership Rewards points.
A travel-focused American Express card may be more relevant.
Neither person needs to choose the same card.
That’s the main idea behind an effective American Express credit card comparison: start with spending habits, then compare rewards, fees and benefits.
Are American Express Cards Worth It?
The answer depends on the individual card and how you use it.
An annual-fee card can make sense when the rewards and benefits you actually use exceed the cost of the fee.
A no-annual-fee card can make sense when you want straightforward rewards without an ongoing annual charge.
A premium travel card can make sense for someone who regularly uses its travel benefits, while the same card may be difficult to justify for someone who rarely travels.
So rather than asking whether American Express credit cards are worth it, compare the card’s expected value with your actual spending and habits.
How to Apply for an American Express Credit Card
The application process generally involves:
- Choose a card.
- Review the current rewards and benefits.
- Read the rates and fees.
- Review eligibility and offer terms.
- Submit an application.
- Review the decision and offer presented to you.
- If approved and you accept, follow the account setup instructions.
American Express currently provides a comparison tool for its U.S. credit cards, allowing consumers to compare different cards and features before applying.
American Express also currently promotes an application process where eligible applicants can find out whether they are approved before choosing to accept a card, with the potential credit-score impact explained as part of the process.
What to Check Before Applying
Before submitting your application, take two minutes to review:
- Annual fee
- Purchase APR
- Introductory APR, if applicable
- Welcome offer
- Spending requirement
- Reward categories
- Reward limits
- Redemption options
- Foreign transaction fee
- Travel benefits
- Statement credits
- Eligibility requirements
- Current cardmember agreement
This small checklist can prevent surprises later.
Frequently Asked Questions
There is no single American Express card that is best for every person. The appropriate card depends on spending habits, desired rewards, annual-fee preferences, travel frequency and how the card will be used.
A beginner may prefer a card with straightforward rewards and manageable costs. No-annual-fee options can be easier to understand, while travel and premium cards may make more sense for people who already understand rewards and can use their benefits.
Yes. For example, the Blue Cash Everyday Card currently has no annual fee. American Express also lists no-annual-fee cards as a category on its U.S. card comparison page.
Cash back is generally provided as Reward Dollars that can be redeemed according to the card’s terms, while Membership Rewards points are a points-based system with multiple potential redemption options.
Some American Express cards have no annual fee, while others charge annual fees. The amount depends on the specific card, so check the current product page and rates and fees before applying.
Membership Rewards points generally do not expire while you maintain at least one active enrolled card, subject to the program’s terms. Other reward programs can have different rules.
A welcome bonus can be valuable, but it should not be the only consideration. Make sure you can meet the spending requirement through normal spending and that the card’s ongoing rewards, fees and benefits fit your needs.
No. Carrying a balance does not make a rewards card more valuable by itself. Interest charges can reduce or eliminate the value of rewards. Paying the balance in full when possible can help avoid purchase interest when the card’s grace-period terms allow it.
Some American Express cards are specifically designed around travel rewards and benefits. The value depends on how frequently you travel and whether you can use the particular card’s travel benefits.
Acceptance depends on the merchant and payment environment. Before relying on an Amex card as your only payment method, especially while traveling, consider carrying another payment option.
Final Takeaway
The right American Express credit card is the one that matches your real spending—not necessarily the card with the biggest headline offer.
Start with your everyday expenses. Then compare cash back versus points, annual fees, APR, reward limits, welcome-offer requirements and benefits.
If you primarily want simple cash back, an American Express cash back card may be worth examining. If you travel frequently, a Membership Rewards or travel-focused card may deserve closer attention. And if you are considering a premium card, calculate whether you will actually use enough of its benefits to justify the annual fee.
Most importantly, review the current American Express terms, rates, fees and benefit conditions before applying, because card offers and benefits can change over time.
A credit card should support your existing spending plan—not encourage spending simply to earn rewards.